

Credit One Bank Mobile
by Credit One Bank, N.A.
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
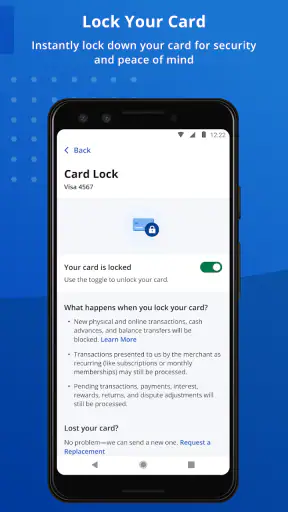
 Analysis by Getfullapps
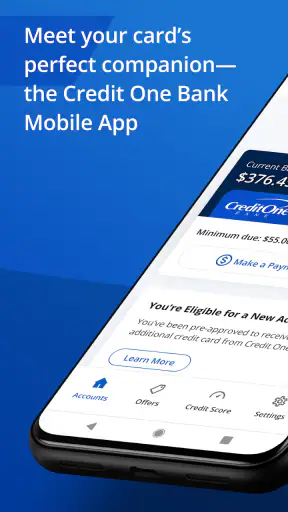
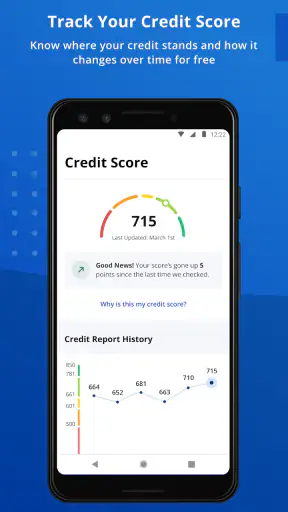
I use finance apps differently from entertainment apps: I want them to open quickly, show the information I need without confusion, and get out of the way when I am checking a purchase or making a payment. Credit One Bank Mobile is built for that focused job. It is a free finance app from Credit One Bank, N.A. that lets cardholders manage their credit card account from an Android or iOS device. After spending time with it, I see it as a practical companion for routine account checks rather than a complete personal-finance command center.
The app has been available since September 19, 2016, and its current version is 26.07.0. Its age rating is Everyone, so it is suitable for a broad audience, although the usefulness naturally depends on having a Credit One Bank card account. It has reached over ten million installs, with a 4.7 average from around 832,000 ratings and about 213,000 written reviews. Those figures suggest that the app has become a familiar tool for a large number of cardholders, but they do not remove the need to judge whether its particular workflow suits you.
How Credit One Bank Mobile feels in everyday use
I find it most useful to treat this as a card-account check-in, not a place to make every financial decision. A quick look can help me notice an unfamiliar purchase or prepare for a planned expense, while a careful reconciliation still calls for receipts and statements. That distinction also shapes how I judge the app’s trustworthiness: next, I look at the controls and choices a user can actually verify.
Quick checks are where it makes the strongest impression
My first impression is that the app makes sense when I treat it as a pocket window into my card account. The most useful moments are short ones: checking whether a recent purchase has appeared, looking at the available credit before buying something, or confirming that I am looking at the right account before taking action. That narrow purpose helps the experience feel more direct than opening a general banking app and searching through several unrelated sections.
Perceived speed matters especially in these situations. When I am standing at a checkout, comparing a receipt with my account, or trying to remember how much room remains on a card, I do not want to navigate through a complicated financial dashboard. Credit One Bank Mobile is at its best when I open it with one clear question and leave soon after finding the answer. The app is not trying to replace every money tool on my phone, and that restraint is useful.
There is also a practical difference between checking an account and managing an entire budget. A dedicated card app can show the information most relevant to that card without mixing it with savings goals, investment balances, or accounts from other institutions. For someone who wants a focused view of Credit One Bank activity, that can feel cleaner than a third-party finance app that gathers everything together but adds another layer of organization.
A realistic day-to-day scenario
Imagine that I buy household supplies in the morning and later notice that the total looks higher than expected. I can open the app, inspect the account activity, and compare the posted or visible transaction with the receipt. If I am planning another purchase, I can also use the account view to make a more informed decision about available credit. This small routine is more valuable than it sounds because it turns account awareness into a habit instead of something I remember only when a statement arrives.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The same workflow helps after a busy weekend. Rather than trying to reconstruct spending from memory, I can review the card activity while the purchases are still familiar. That makes it easier to spot a duplicate-looking charge, recognize a subscription renewal, or identify a purchase that needs a closer look. I would not rely on an app alone to resolve a serious account problem, but having the account visible on demand makes the first step much easier.
One tip I found useful is to open the app with a specific task in mind. “Check the balance,” “review a purchase,” and “handle the account” are different intentions. The first two encourage a fast visit; the last can lead to unnecessary browsing. This sounds simple, but it reduces the chance of making a rushed decision based on one number without checking the surrounding account information.
Where speed can feel less predictable
Finance apps depend on more than the phone itself. The app may need to communicate with the bank before it can show current account information, so a fast device does not guarantee an instant result. A weak mobile connection, a crowded network, or temporary service delay can make a simple check feel slower. I consider that an important distinction: the app can be responsive as an interface while still waiting for account data.
That is why I would avoid opening it for the first time at the exact moment a payment decision must be made. If I know I will need to check available credit before a trip or a large purchase, I prefer to review the account earlier. This is not a criticism unique to Credit One Bank Mobile; it is a sensible habit for any app that depends on live financial information. The useful insight is that planning around the app’s purpose makes perceived speed much better.
For ordinary account monitoring, I do not need elaborate animation or a large collection of extras. I value a clear path to the account information more than visual polish. The app’s strongest performance quality is therefore functional: it is meant to help me complete a financial check, not keep me inside the application.
What happens during heavier use?
“Heavy use” here does not mean gaming or editing video. It means several account tasks in one sitting: reviewing a series of transactions, moving between account areas, checking details, and returning to the main view. That kind of session puts more pressure on navigation and data refreshes than a quick balance check. I find it important to separate those two experiences because an app can feel perfectly adequate for a single glance yet become less comfortable when I ask it to support a longer review.
Credit One Bank Mobile is most useful for focused account maintenance, so I would not make it my only tool for analyzing months of spending. If I want categories, long-term trends, or a combined picture across several financial institutions, a dedicated budgeting service or a broader banking dashboard may be better. The trade-off is straightforward: the bank’s own app is closer to the card account, while a general finance tool may be stronger at comparisons and planning.
A concrete workflow helps here. I would first review the newest activity, then note any purchase that needs attention, and only afterward look at the overall account position. Separating those steps prevents me from repeatedly refreshing or jumping between screens without a purpose. It also makes the app feel lighter because I am not asking it to serve as a spreadsheet.
Another useful habit is to distinguish pending-looking activity from the amount I ultimately need to reconcile. Card transactions can change status as merchants complete processing, and a quick glance is not always the same as a final accounting. I would use the app to stay aware, but I would still compare the information with receipts and statements when accuracy matters for budgeting. That is a limitation of relying on a live card view for detailed financial records, not a reason to dismiss the app.
Reliability and recovering from interruptions
Reliability in a finance app has two parts. The first is whether the application opens and lets me move around. The second is whether it can recover sensibly when the connection or account session is interrupted. The second part is easy to overlook until I am checking a transaction in a place with unstable reception or returning to the app after switching to another task.
My advice is to treat an interrupted session conservatively. If a screen takes longer than expected or the app returns from the background in an unusual state, I would not immediately repeat a payment-related action. I would first return to the account view and verify what has actually happened. That extra pause is especially important in financial software because repeating an action out of frustration can create confusion.
The app is also more dependable as a monitoring tool when I use it regularly rather than only during a crisis. Frequent short visits help me notice familiar account behavior, so an unexpected transaction stands out sooner. This is one of the less obvious advantages of a dedicated card app: it can support a simple review routine without requiring me to maintain a separate manual log for every ordinary purchase.
Still, I would not confuse convenience with a complete support channel. If an account issue is urgent or the displayed information does not match my records, I would follow the bank’s normal assistance process instead of repeatedly refreshing the app. The application is a useful first point of visibility, but serious discrepancies deserve direct attention.
Device limits and who should think twice
The listed minimum operating-system requirement is version 10. That is not an extreme demand for a modern phone, but it matters if I am using an older device that no longer receives regular system updates. Before installing, I would check the phone’s operating-system version rather than assuming that any Android or iOS handset will work. A compatible system is the starting point for judging speed and stability; otherwise, an app review becomes a hardware problem.
On a supported phone, the app’s resource demands are likely to matter less than the quality of the connection and the condition of the device. I would not choose it for a phone that is already struggling with storage, background processes, or outdated system software, because those issues can make every finance app feel unreliable. Keeping the operating system current and closing unusually demanding background tasks is a more useful performance step than expecting the app to compensate for an aging device.
People who share devices should also think about privacy in practical terms. A finance app places account access close to other everyday activities, so I would use the phone’s own screen lock and avoid leaving the account open where someone else can casually pick up the device. I am not presenting that as a special feature of this app; it is simply the sensible way to use any mobile banking tool.
The app may not be the right choice for someone who does not hold a Credit One Bank card, wants one unified view of several banks, or needs sophisticated expense categorization. In those cases, a broader personal-finance app can offer a better overview. I would also skip making it my primary budgeting system if I need detailed reports, long-range planning, or extensive customization. Its value comes from direct card management, not from trying to cover every financial task.
How it compares with the usual alternatives
The most obvious alternative is using a mobile browser to reach the bank’s account site. I generally prefer a dedicated app for repeated checks because it feels more natural on a phone and keeps the task separate from ordinary browsing. A browser can be useful on a shared or temporary device, though, and it may be the better fallback when I cannot install the app or when I am using a phone that does not meet the minimum operating-system requirement.
A second alternative is a general budgeting application. That option wins when I want to combine Credit One Bank activity with other cards, checking accounts, or household spending plans. It can make the bigger financial picture easier to understand. The compromise is that I am relying on an additional service and a broader interface for information that the bank’s own app is designed to present directly. For a quick card check, Credit One Bank Mobile is the more focused choice; for cross-account planning, the general tool is usually stronger.
Another alternative is waiting for paper statements or using a desktop computer. Those methods can be comfortable for a careful monthly review, especially when I want a larger screen. They are less convenient for catching an unfamiliar purchase soon after it appears. I see the mobile app as complementary rather than a total replacement: it supports frequent awareness, while a statement or larger-screen review can support more deliberate reconciliation.
My performance verdict
Credit One Bank Mobile succeeds when I use it for what it is: a focused finance app for managing a Credit One Bank card account. Its free price removes a common barrier to trying it, and the broad Everyone age rating makes it approachable for ordinary household use. The large install base and strong average rating show that it is widely used, though my recommendation rests more on the practical workflow than on popularity.
The best reason to use it is quick, direct account awareness without turning every check into a full budgeting session. I would install it if I held a Credit One Bank card and wanted a convenient way to review activity and stay closer to my account during the week. I would prepare for occasional delays caused by connectivity or account-data refreshes, and I would verify important actions instead of repeating them when a screen behaves unexpectedly.
In my view, the app is a good fit for cardholders who value focused access, short routine visits, and a bank-specific account view. It is less suitable for people seeking a complete financial planning suite, combined account management, or deep spending analysis. The current version, 26.07.0, supports the present experience, while the minimum requirement of version 10 means older devices should be checked before installation. If those conditions match your situation, Credit One Bank Mobile is a sensible everyday tool rather than an unnecessarily complicated financial dashboard.
I would recommend building a small routine around it: review recent activity after meaningful purchases, check the account before a planned large expense, and use a statement or broader budgeting method when you need a complete financial picture. Used that way, Credit One Bank Mobile feels most valuable—not because it tries to do everything, but because it puts the card information I actually need within reach at the moment I need it.
Pros
- User-friendly interface with intuitive navigation.
- Quick access to account details and transactions.
- Secure login with fingerprint or facial recognition.
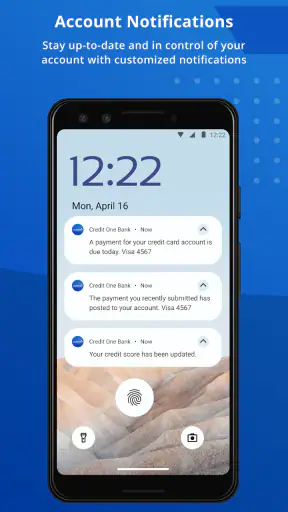
- Real-time notifications for account activities.
- Easy credit card payment management.
Cons
- Limited customer support options within the app.
- Occasional glitches with transaction updates.
- No budgeting or financial planning features.
- In-app advertisements can be distracting.
- High data usage with frequent app updates.
FAQs for Credit One Bank Mobile
What features does the Credit One Bank Mobile app offer?
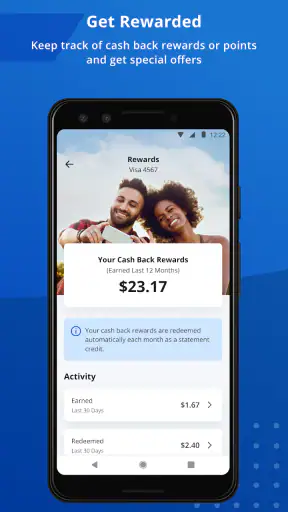
The Credit One Bank Mobile app provides users with a range of features designed to manage their credit card accounts efficiently. These include checking account balances, viewing recent transactions, making payments, and setting up account alerts. Additionally, users can access exclusive offers and manage their rewards directly from the app.
Is the Credit One Bank Mobile app secure to use?
Yes, the Credit One Bank Mobile app is designed with security as a top priority. It uses encryption and other advanced security measures to protect your personal and financial information. Users can also enable fingerprint or facial recognition for added security when accessing their accounts.
Can I manage multiple accounts with the Credit One Bank Mobile app?
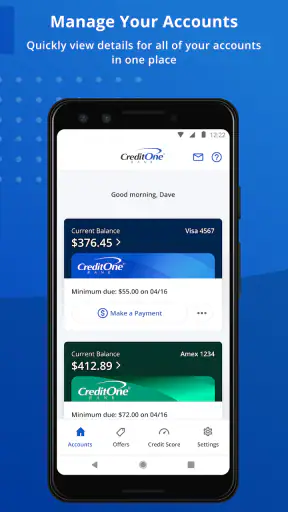
Yes, the app allows users to manage multiple Credit One Bank accounts. You can easily switch between accounts to view balances, recent transactions, and payment due dates. This feature makes it convenient for users who have more than one credit card with Credit One Bank.
How can I make payments using the Credit One Bank Mobile app?
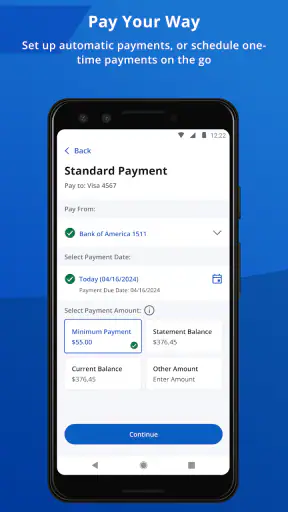
Making payments through the app is straightforward. Users can set up one-time or recurring payments directly from their linked bank accounts. The app also provides reminders for upcoming due dates to help avoid late fees, ensuring that payments are made on time.
Is the Credit One Bank Mobile app available for both Android and iOS devices?
Yes, the Credit One Bank Mobile app is available for both Android and iOS platforms. Users can download the app from the Google Play Store for Android devices or the Apple App Store for iOS devices. Regular updates ensure compatibility and improved functionality across both platforms.

Credit One Bank Mobile
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via AppStoreDevAcct@creditone.com, visit https://www.creditonebank.com/, or review their https://www.creditonebank.com/legal/privacy.










